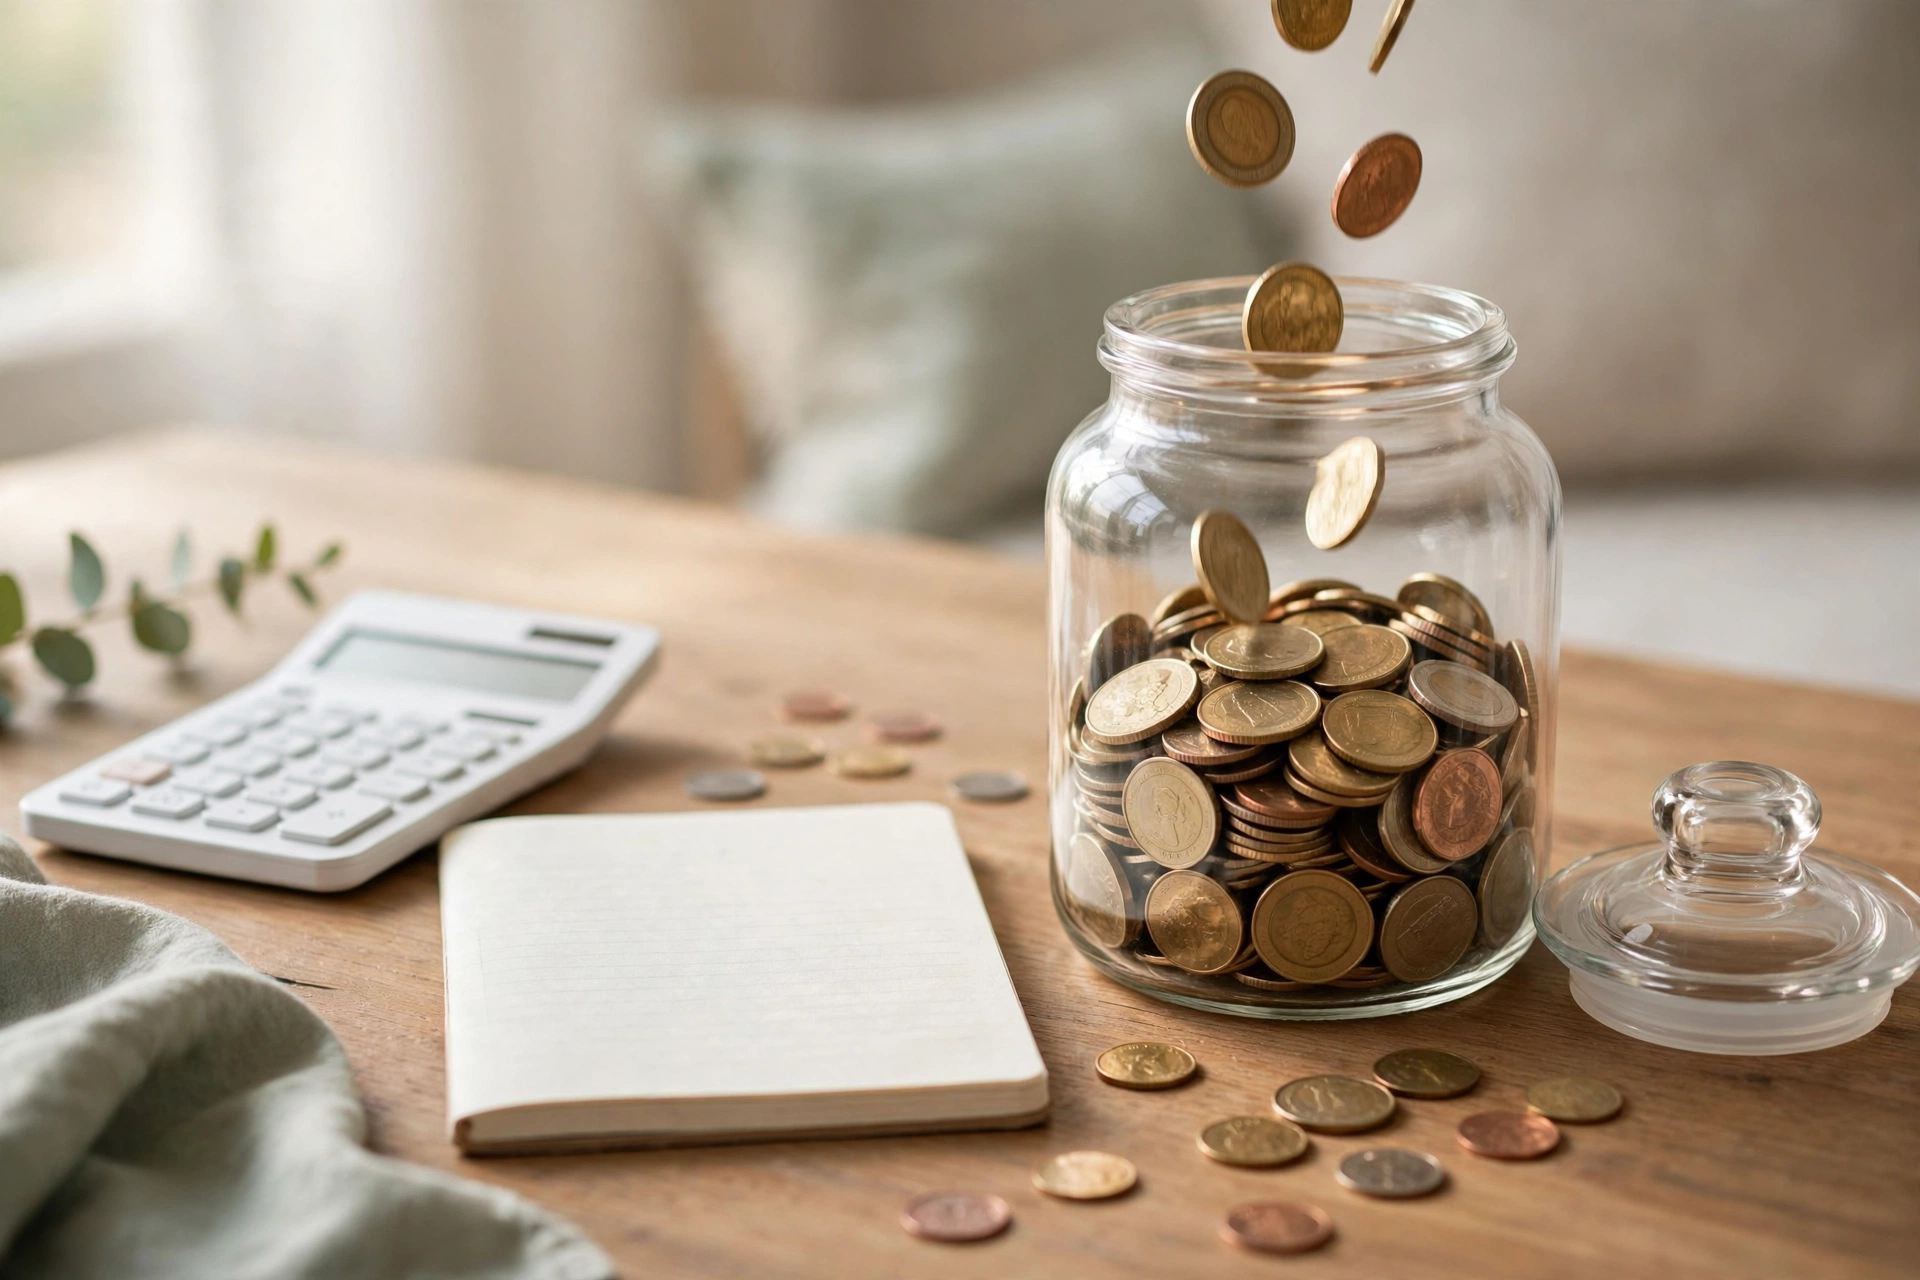
An emergency fund is money you set aside for the unexpected: a broken boiler, a car repair, a sudden medical bill, or a few months without work. It is not an investment and it is not a holiday fund — it is a financial cushion that stops a bad week from turning into debt. Personal finance experts agree on one thing above almost everything else: before you invest, before you pay extra on a mortgage, before you chase higher returns, build an emergency fund. This guide explains how much you need, where to keep it, and how to build it step by step, even on a modest income.
Why an Emergency Fund Comes First
Life is unpredictable, and the cost of being unprepared is high. Without savings, a $500 car repair goes on a credit card at 20 percent interest, and a $500 problem becomes a $700 problem. With a fund in place, the same repair is an annoyance, not a crisis. An emergency fund also changes how you make decisions: you can leave a bad job, turn down a risky commitment, or handle a medical issue without panic. It is the foundation of every other financial goal, because it protects the money you are trying to grow. If you already have a plan for how much money to keep in a high-yield savings account, an emergency fund is the first and most important use for that account.
How Much Should You Save?
The standard advice is three to six months of essential expenses — not your full income, but the amount you must spend to live: rent or mortgage, food, utilities, transport, insurance, and minimum debt payments. Three months is a reasonable target if you have a stable job and a second income in the household; six months is wiser if you are self-employed, work in an unstable industry, or are the sole earner. Start with a smaller milestone first: $1,000 (or one month of expenses) is a realistic first goal that already covers most common emergencies, such as a car repair or a broken appliance. Once you reach it, keep going toward the three-month mark, then six.
To find your number, add up one month of essential spending, then multiply by three or six. If your essentials are $2,000 a month, your target is $6,000 to $12,000. That sounds large, but you do not need it tomorrow — you build it gradually, and every dollar in the fund makes you safer than you were the day before.
Where to Keep Your Emergency Fund
An emergency fund must be safe, accessible, and separate from your everyday spending. A high-yield savings account is the most popular choice: it pays far more interest than a regular savings account, your money is not at risk, and you can withdraw it within a day or two when you need it. Keep it in a different bank from your main current account if you can — the small delay in moving money is a feature, not a flaw, because it stops impulse spending while still being fast enough for a genuine emergency. Avoid keeping it in investments, shares, or cryptocurrency, because their value can fall exactly when you need the money, and avoid keeping it in cash at home, where it earns nothing and can be lost or stolen.
How to Build It Step by Step
Start by opening a dedicated savings account and giving it a clear name, such as “Emergency Fund”. Then set up an automatic transfer on payday — even $25 or $50 a week adds up to $1,300 to $2,600 in a year. Treat the transfer as a bill you cannot skip. Next, find money you are already spending without noticing: cancel a subscription you do not use, cook at home two more nights a week, or sell things you no longer need, and send the savings straight into the fund. When you receive a tax refund, a bonus, or a gift, put at least half of it into the fund before you spend any of it. Finally, track your progress monthly — watching the balance grow is motivating, and it turns saving from a chore into a habit.
When to Use It — and When Not To
An emergency fund is for true emergencies: a job loss, a medical bill, an essential car or home repair, or an unexpected expense you cannot postpone. It is not for holidays, a new phone, a sale you do not want to miss, or a night out. The test is simple: if you can delay the spending or it is something you want rather than need, it is not an emergency. After you use the fund, rebuilding it becomes your top financial priority — restore the automatic transfer and top it up before resuming other goals. A fund that is empty after one emergency is a sign it was too small, not a sign the idea failed.
Common Mistakes People Make With Emergency Funds
The most common mistake is waiting for the perfect moment to start. There is no perfect moment; the best time is your next payday, with whatever amount you can manage. Another is keeping the fund in the same account as everyday spending, where it quietly gets spent. A third is investing it for higher returns, then discovering it has fallen by a fifth when you need it most. Many people also set the goal too high and give up — a $12,000 target feels impossible, while a $1,000 milestone feels achievable, and reaching it builds momentum. Others raid the fund for non-emergencies and never rebuild it, which leaves them exposed. And some people save diligently but keep high-interest debt at the same time; if you carry credit card debt, it usually makes sense to clear the most expensive debt first while building a small starter fund, then grow the fund once the debt is gone.
Frequently Asked Questions
How much should I have in an emergency fund?
Aim for three to six months of essential expenses. Start with $1,000 or one month of expenses as your first milestone, then build toward three months, and finally six if your income is variable or you are the sole earner.
Where is the best place to keep an emergency fund?
A high-yield savings account is the best choice for most people: it is safe, earns reasonable interest, and you can access the money within a day or two. Keep it separate from your everyday spending account.
Should I pay off debt or build an emergency fund first?
Do both in sequence: build a small starter fund of around $1,000 first, then attack high-interest debt, then grow the fund to three to six months of expenses. The starter fund stops new emergencies from adding to your debt.
How fast can I build an emergency fund?
It depends on how much you can save each month. Saving $200 a month reaches $1,000 in five months and $2,400 in a year. Automating the transfer on payday makes it happen without relying on willpower.
Can I invest my emergency fund?
No. An emergency fund must be stable and instantly available. Investments can fall in value at the worst moment, which defeats the purpose. Invest only money you do not need for at least five years.
What counts as an emergency?
A job loss, a medical bill, an essential car or home repair, or an unavoidable expense you cannot delay. Holidays, new gadgets, sales, and gifts are not emergencies, even if they feel urgent.
Do I still need an emergency fund if I have insurance?
Yes. Insurance covers specific risks and often comes with deductibles and delays. An emergency fund covers everything else — the excess on a claim, the costs insurance does not cover, and the weeks between a loss and a payout.